CSL has already doubled off its May lows. Will Dougal Maple-Brown’s other shocking prediction land?
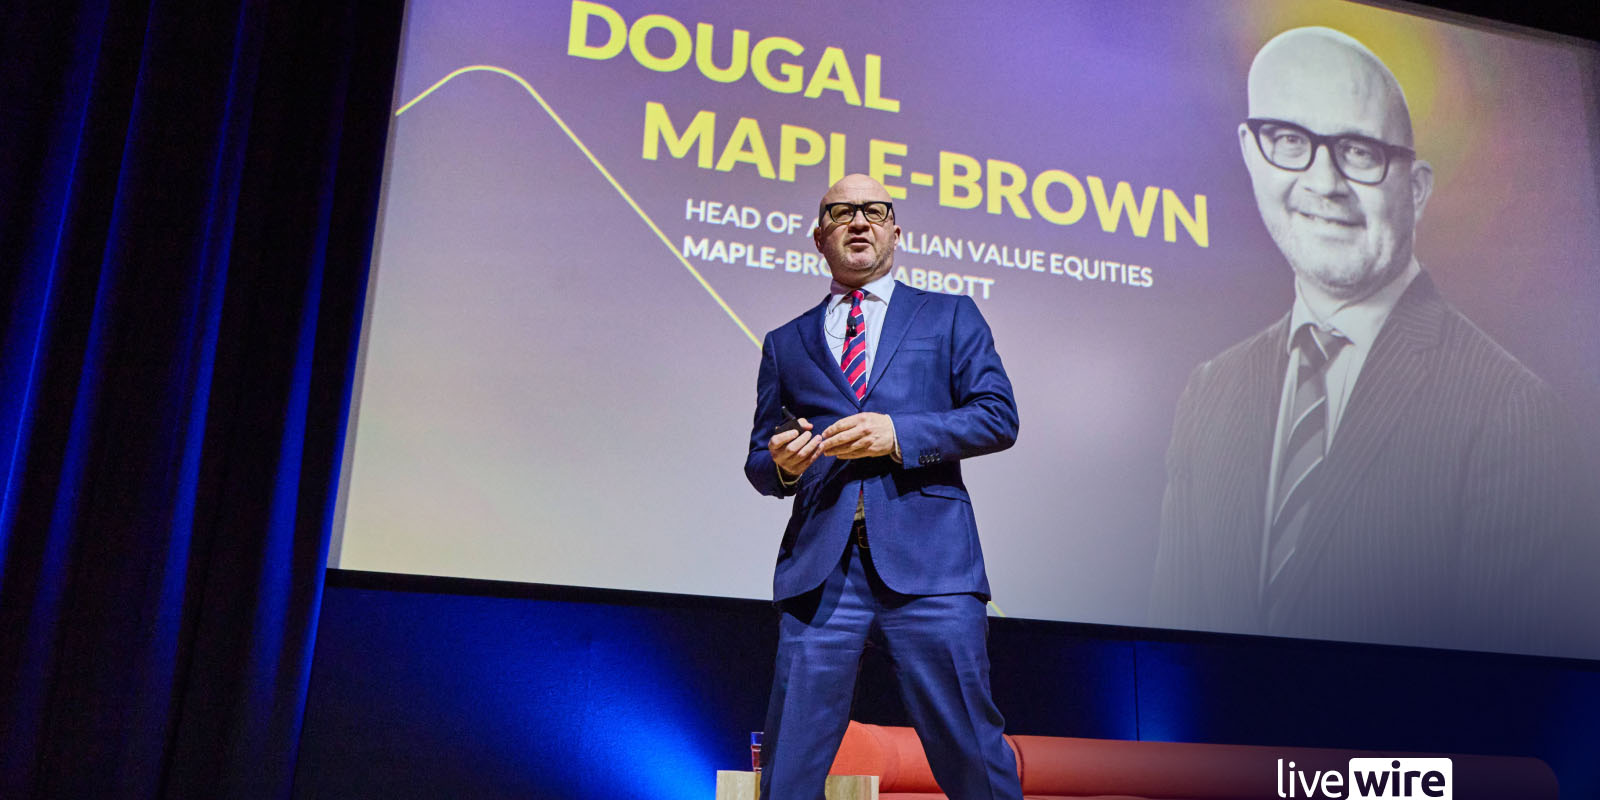
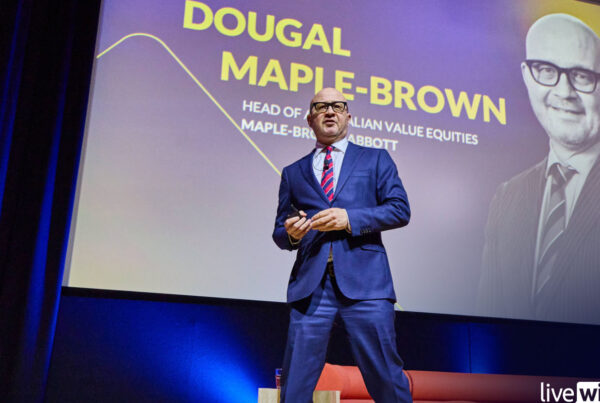
In the gap between Head of Australian Value Equities Dougal Maple-Brown agreeing to deliver a shocking prediction at Livewire Live about a month ago and his presentation, one half of it had already hit.
“My shocking prediction is that CSL will double off its lows, and CBA will halve off its highs,” Maple-Brown said.
CSL (ASX: CSL) hit decade lows in May of around $90, trading at just 10x forward earnings, which is a far cry from its former glory when it peaked at $300 and traded at 50x. Maple-Brown Abbott didn’t hold any at the peak but bought a lot when it fell.
“To double off $90 at 10x, you can do it lots of ways. The simplest, and what’s largely happened, is earnings have been flat but the multiple has doubled. CSL I think almost went through $180 this morning.”
“As the stock has been re-rated from about 10 times earnings to about 20 times earnings, maybe that doesn’t count as shocking, but the next one does.”
The reason that CSL surged so quickly is that the former powerhouse had simply gotten too cheap and even a fairly flat result in August was enough to push the price higher. Or, in Maple-Brown’s words: “Valuations always matter.”
CBA is heading to $100
CBA (ASX: CBA) is about as entrenched in Australian investors’ portfolios as a stock can get, but should it still be? Long the poster child for “priced for perfection”, CBA has traded effectively +/-10% in the last 12 months, despite the wall of worries spanning its high price-to-earnings multiples (currently mid 20x).
These valuation concerns are driving a broker consensus that CBA is overpriced, however few are quite as low on the future outlook for Australia’s largest bank as Maple-Brown.
CSL 1-year
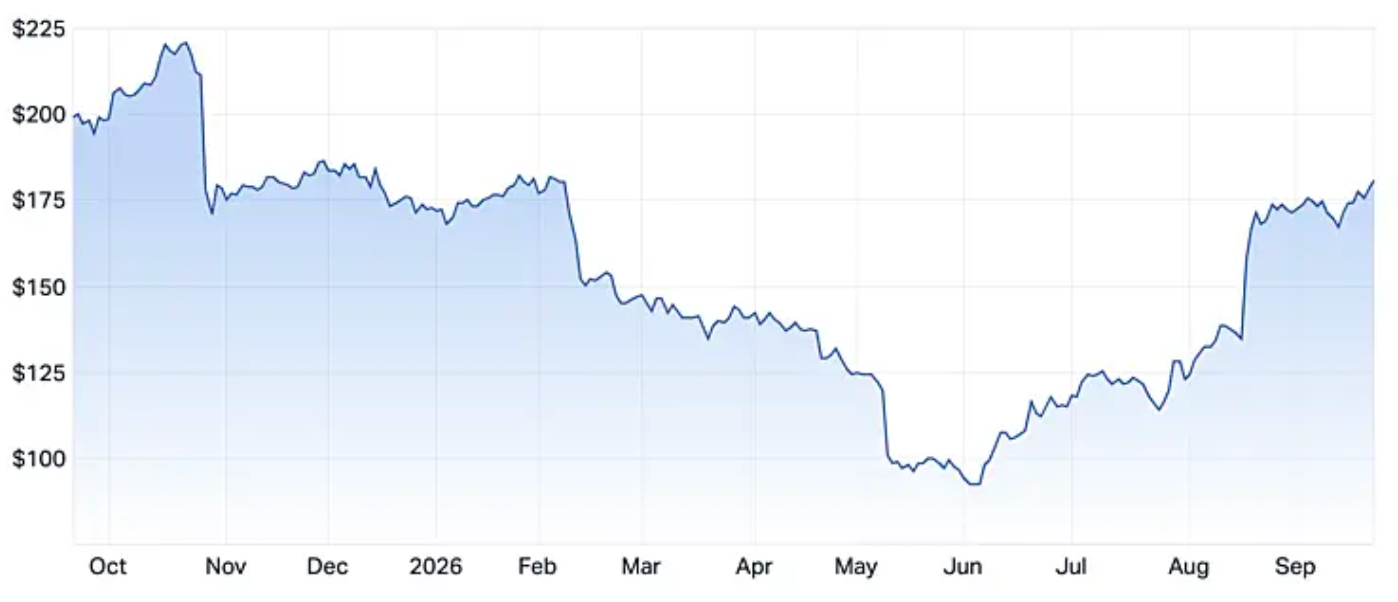
Source: Markt index
“My shocking prediction is that CBA goes from, in round numbers, $200 a share down to $100 a share. Why I say that call is still very live today is it’s about $160 a share, give or take,” Maple-Brown said.
The reason? Once again, it’s all about valuation.
“CBA was trading on around 30 times forward earnings. The most expensive bank in the world – daylight was second, third, fourth, and fifth.”
The other big four banks, however, are trading around 15 times earnings. Essentially, all CBA needs to do is trade like its peers and Maple-Brown’s prediction will be right. Also playing into the prediction is that the fund is underweight banks across the board.
“We are heavily underweight for banks, and we have zero CBA. Credit growth is slowing, costs are rising, credit losses are likely to rise depending on how good your crystal ball is with property prices. All of which means earnings are going to be flat at best.
“If you’ve got a big bearish housing scenario, a big bearish recession scenario, earnings are going to go backwards. So, CBA’s share price could halve whether the ratio halves or maybe only goes to 16 or 17 times, but the earnings go back a little bit. I don’t find any of those things particularly shocking.”
While only one of the calls still falls in the “shocking prediction” camp, the thesis on valuation being proved right so quickly for CSL backs up Maple-Brown’s overall point.
“All we care about is valuation, that’s how we build our portfolios. We are totally agnostic to AI, to data centres, to picks and shovels, whatever the thematic of the day is. All we care about is valuation.
“We are overweight healthcare today for the first time in decades. We are more underweight Australian banks today than any time in the 40 years of our existence, because valuation matters.”
Disclaimer
This video is prepared and issued by Maple-Brown Abbott Limited ABN 73 001 208 564, AFSL 237296 (‘MBA’) as the Responsible Entity of the MBA Australian Value Opportunities Fund (ARSN 091 138 233) (‘Fund’) and the MBA Australian Share Fund – Wholesale (ARSN 087 294 504) (‘Fund’). This video contains general information only, and does not take into account your investment objectives, financial situation or specific needs. Before making any investment decision, you should seek independent financial advice. This document does not constitute an offer or solicitation by anyone in any jurisdiction. Past performance is not a reliable indicator of future performance. Neither MBA, nor any of its related parties, directors or employees, make any representation or give any guarantee as to the return of capital, performance, any specific rate of return, or the taxation consequences of, any investment.
Any views expressed on individual stocks or other investments, or any forecasts or estimates, are not a recommendation to buy, sell or hold, they are point in time views and may be based on certain assumptions and qualifications not set out in part or in full in this document. Individual stocks referred to may or may not be currently held by the Fund. Information derived from sources is believed to be accurate, however such information has not been independently verified and may be subject to assumptions and qualifications not described in this document. To the extent permitted by law, neither MBA, nor any of its related parties, directors or employees, make any representation or warranty as to the accuracy, completeness, reasonableness or reliability of this information, or accept liability or responsibility for any losses, whether direct, indirect or consequential, relating to, or arising from, the use or reliance on this information. Before making a decision whether to acquire, or to continue to hold an investment in the Fund, investors should obtain and consider the current PDS and Target Market Determination (TMD) or any other relevant disclosure document. For the Fund, the PDS, AIB and TMD are available at maple-brownabbott.com/document-library or by calling T +61 2 8059 7671. This information is current as of 23 September 2026 and is subject to change at any time without notice. © 2026 Maple-Brown Abbott Limited.
Dougal joined Maple-Brown Abbott in 2001 as an equity analyst. He is currently a portfolio manager and equities analyst. Dougal was an Executive Director from July 2009 to October 2018. Dougal’s responsibilities include equity analysis and portfolio management, including managing a large number of institutional and retail accounts. He attended the Advanced Management Program at Harvard Business School in 2014. Prior to joining Maple-Brown Abbott Dougal worked in a national law firm and at an international investment bank.
Board and committee membership:
Asset Allocation Committee
Dougal
Interested in investing with us?
Investment Insights
Dougal Maple-Browns shocking prediction
Data center growth in Iberia
2026 Australian Small Companies ESG Report
Beyond the chips five thematics from our US trip